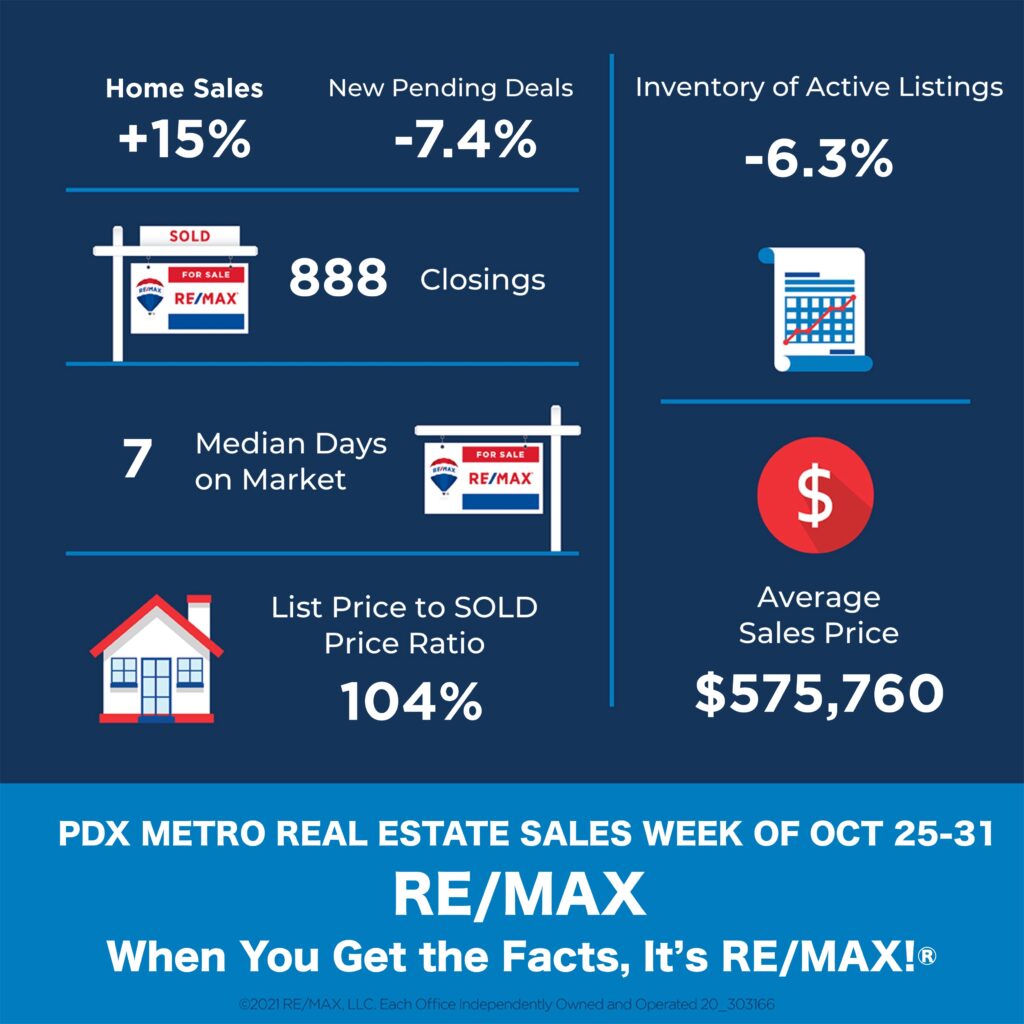
Numbers Don’t Lie – It’s Still a Great Time To Sell [INFOGRAPHIC]

Numbers Don’t Lie – It’s Still a Great Time To Sell [INFOGRAPHIC] | MyKCM

Some Highlights

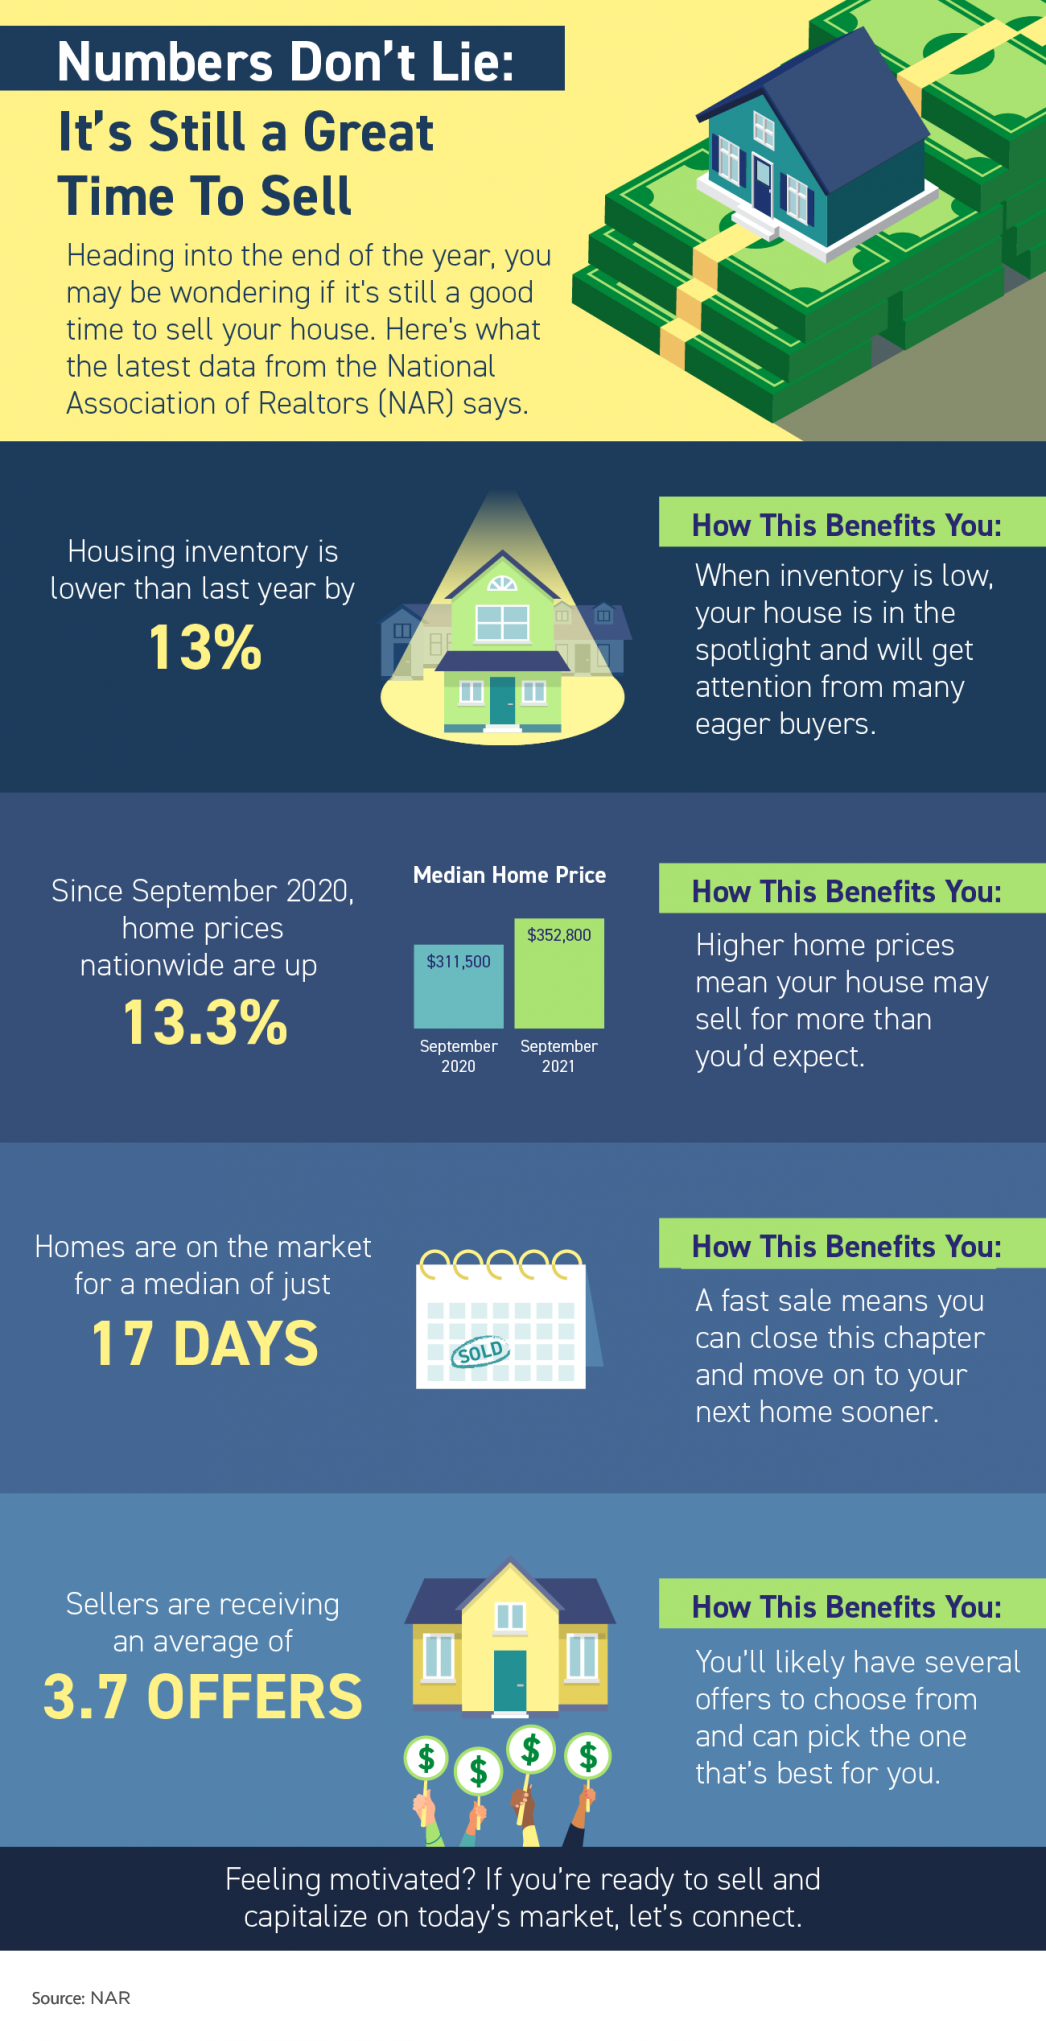
  • Heading into the end of the year, you might wonder if it’s still a good time to sell your house. Here’s what the latest data from the National Association of Realtors (NAR) says.
  • Housing supply is lower than last year, and home prices are up nationwide. Meanwhile, the average home is selling fast and receiving several offers. Listing now puts your house in the spotlight, meaning it could sell quickly – and for more than you’d expect.
  • Feeling motivated? If you’re ready to sell and capitalize on today’s market, let’s connect.

Mortgage rates decline to 3.09%

Rates dropped from 3.14% in the prior week, according to Freddie Mac’s PMMS

November 4, 2021, 10:00 am By Flávia Furlan Nunes

Mortgage rates decline to 3.09%

The average 30-year-fixed rate mortgage dropped to 3.09% during the week ending Nov. 4, down from 3.14% the week prior, according to the latest Freddie Mac PMMS Mortgage Survey. A year ago, the 30-year fixed-rate mortgage averaged 2.78%.

Most economists believe mortgage rates will climb following as the Federal Reserve tightens monetary policy. The central bank’s Federal Open Markets Committee announced on Wednesday that it will begin to taper its monthly asset purchases starting in November.

“While mortgage rates fell after several weeks on the rise, we expect future upticks due to stronger economic data and as the Federal Reserve pulls back on its stimulus,” Sam Khater, Freddie Mac’s chief economist, said in a statement.

Mortgage rates tend to move in concert with the 10-year Treasury yield, which reached 2% yesterday, after five weeks below the 2% level. The 15-year-fixed-rate mortgage averaged 2.35% last week, down from 2.37% the week prior. A year ago at this time, it averaged 2.32%.

The tapering will begin soon thanks to economic “substantial further progress,” according to the central bank. It will reduce the pace of its $120 billion in monthly purchases by $10 billion for Treasury securities and $5 billion for agency mortgage-backed securities.

“Progress on vaccinations and an easing of supply constraints are expected to support continued gains in economic activity and employment as well as a reduction in inflation,” the Fed said. “Risks to the economic outlook remain.”

Later this month, the Federal Reserve will purchase at least $70 billion Treasury securities and at least $35 billion agency mortgage-backed securities.   

Rising mortgage rates have already begun to sap demand. Mortgage application activity dropped 3.3% for the week ending Oct. 29, according to the most recent Mortgage Bankers Association (MBA) survey. The Refinance Index decreased 4% in one week, while the Purchase Index dropped 3% in the same period.

Joel Kan, MBA’s Associate Vice President of Economic and Industry Forecasting, said that mortgage rates decreased for the first time since August due to concerns about supply-chain bottlenecks, waning consumer confidence, weaker economic growth, and rising inflation.

Profit Margins on U.S. Home Sales Spike to Decade High in Q3

By David Barley | November 4, 2021 8:06 AM ET

https://www.worldpropertyjournal.com/real-estate-news/united-states/irvine/real-estate-news-to-attom-data-third-quarter-2021-us-home-sales-report-median-home-prices-in-2021-todd-teta-rising-home-price-data-12804.php

Median Home Prices Reach New Record High in North America

According to ATTOM Data’s newest quarterly U.S. Home Sales Report, profit margins on median-priced single-family home and condo sales across the United States jumped to 47.6 percent – the highest level since the end of the Great Recession a decade ago.

In yet another sign of how strong the U.S. housing market remains, the report reveals that the typical home sale across the country during the third quarter of 2021 generated a profit of $100,178 as the national median home price hit a record of $310,500. The latest profit level – also a new high – was up from $88,800 in the second quarter of 2021 and from $69,000 in the third quarter of 2020.

Those gains raised the typical return on investment that sellers made on their original purchase price nationwide from 42 percent in the second quarter of this year and 34.5 percent a year earlier. The investment-return increases marked the biggest quarterly jump since 2014 and the biggest annual surge since at least 2008.

Soaring profits in the third quarter came as the national median home price increased 3.5 percent from the second quarter of 2021 and 15.9 percent from the third quarter of 2020. The annual price surge marked the fifth straight quarter with year-over-year increases of at least 10 percent.

So hot was the national market in the third quarter that median home prices rose annually in 93 percent of U.S. metropolitan areas with enough data to analyze, while profit margins increased in 86 percent.

The latest price and profit improvements reflect a housing market that kept speeding ahead even as the U.S. economy only gradually recovered from widespread damage caused by the Coronavirus pandemic that hit early last year and continues to pose a threat. Amid rock-bottom interest rates and worries about living in congested virus-prone parts of the country, a glut of buyers has been chasing a tight supply of homes for sale over the past year and a half, raising demand and spiking prices.

“The third quarter of this year marked another period in a banner year for a housing market boom that’s steaming ahead through its 10th year. Prices and seller profits again hit new highs since the market started coming back from the Great Recession in 2012,” said Todd Teta, chief product officer at ATTOM. “There have been a couple of small hints of a possible slowdown in recent months, as we head into the normally quiet Fall and Winter seasons. The pandemic also remains a constant presence that could tamp things down. But, for now, the market engine seems to have nothing but high-octane gas in the tank.”

Profit margins rise annually in nearly 90 percent of metro areas around the U.S.

Typical profit margins – the percent change between median purchase and resale prices – rose from the third quarter of 2020 to the third quarter of 2021 in 175 (86 percent) of 204 metro areas around the United States with sufficient data to analyze. Margins also increased from the second to the third quarter of this year in 168 of the 204 metros (82 percent). Metro areas were included if they had at least 1,000 single-family home and condo sales in the third quarter of 2021 and a population of at least 200,000.

The biggest annual increases in profit margins came in the metro areas of Boise City, ID (margin up from 61.4 percent in the third quarter of 2020 to 130.3 percent in the third quarter of 2021); Claremont-Lebanon, NH (up from 41.1 percent to 93.8 percent); Augusta, GA (up from 19.6 percent to 56.6 percent); Raleigh, NC (up from 30.4 percent to 67 percent) and Bellingham, WA (up from 69.5 percent to 105.6 percent).

Aside from Raleigh, the biggest annual profit-margin increases in metro areas with a population of at least 1 million in the third quarter of 2021 were in Detroit, MI (margin up from 43 percent to 68 percent); Rochester, NY (up from 39.4 percent to 63.8 percent); Austin, TX (up from 47.6 percent to 70.9 percent) and Pittsburgh, PA (up from 40.1 percent to 61.9 percent).

Profit margins stayed the same or dropped, year over year, in just 29 of the 204 metro areas analyzed (14 percent) while they declined quarterly in 36 (18 percent). The biggest annual decreases were in Salem, OR (margin down from 75.6 percent in the third quarter of 2020 to 48.3 percent in the third quarter of 2021); Brownsville, TX (down from 37.1 percent to 13 percent); Kansas City, MO (down from 43.6 percent to 25.1 percent); San Jose, CA (down from 86.2 percent to 71 percent) and McAllen, TX (down from 33.4 percent to 19.9 percent).

Aside from Kansas City and San Jose, the largest annual drops in profit margins among metro areas with a population of at least 1 million came in Los Angeles, CA (down from 54.3 percent to 44.5 percent); Cleveland, OH (down from 32.8 percent to 25.7 percent) and Las Vegas, NV (down from 43.8 percent to 37.2 percent).

Largest profit margins again in West; smallest in South

The West continued to have the largest profit margins on typical home sales around the country, with eight of the top 10 returns on investment in the third quarter of 2021 from among the 204 metropolitan areas with enough data to analyze. They were led by Boise City, ID (130.3 percent return); Bellingham, WA (105.6 percent); Claremont-Lebanon, NH (93.8 percent); Spokane, WA (87.7 percent) and Prescott, AZ (84.7 percent).

Eleven of the 15 smallest margins were in the South region of the country. The lowest were in Shreveport, LA (2 percent); Gulfport, MS (7.4 percent); Columbus, GA (9.9 percent); Atlantic City, NJ (12.4 percent) and Brownsville, TX (13 percent).

Prices up at least 10 percent in two-thirds of nation

Median home prices in the third quarter of 2021 exceeded values from a year earlier by at least 10 percent in 136 (67 percent) of the 204 metropolitan statistical areas with enough data to analyze. Nationally, the median price of $310,500 in the third quarter was up from $300,000 in the second quarter of 2021 and $268,000 in the third quarter of last year.

The biggest year-over-year increases in median home prices during the third quarter of 2021 came in Worcester, MA (up 42.9 percent); Barnstable, MA (up 32.5 percent); Boston, MA (up 28.4 percent); Boise, ID (up 28.3 percent) and Lakeland, FL (up 27.8 percent).

Aside from Boston, the largest annual increases in metro areas with a population of at least 1 million in the third quarter of 2021 were in Austin, TX (up 26 percent); Phoenix, AZ (up 25.5 percent); Las Vegas, NV (up 22.8 percent) and Tucson, AZ (up 22.4 percent).

Home prices in the third quarter of 2021 hit or tied all-time highs in 84 percent of the metro areas in the report, including New York, NY; Los Angeles, CA; Chicago, IL; Dallas, TX, and Houston, TX.

The largest year-over-year decreases in median prices during the third quarter of 2021 were in Brownsville, TX (down 11.9 percent); Pittsburgh, PA (down 10.1 percent); Gulfport, MS (down 8.8 percent); Santa Maria, CA (down 7 percent) and Charleston, SC (down 4.9 percent).

Homeownership tenure remains at eight-year low

Homeowners who sold in the third quarter of 2021 had owned their homes an average of 6.31 years, virtually unchanged from 6.29 years in the second quarter of 2021 and down by more than a year from 7.85 years in the third quarter of 2020. The last two quarters marked the shortest times between purchase and resale since the first quarter of 2013.

Among 109 metro areas with sufficient data to analyze, tenure decreased from the third quarter 2020 to the same period this year in 101 (93 percent). They were led by Lakeland, FL (tenure down 74 percent); Tucson, AZ (down 53 percent); Madera, CA (down 44 percent); Springfield, MA (down 43 percent) and Memphis, TN (down 43 percent).

Fifteen of the 20 longest average tenures among sellers in the third quarter of 2021 were in the Northeast or West regions. They were led by Manchester, NH (10.09 years); Bellingham, WA (9.91 years); Lake Havasu City, AZ (9.69 years); Kahului-Wailuku-Lahaina, HI (9.21) and Rockford, IL (8.81 years).

The smallest average tenures among third-quarter sellers were in Lakeland, FL (1.97 years); Bremerton, WA (2.79 years); Portland, ME (3.39 years); Gulfport, MS (4.05 years) and Tucson, AZ (4.06 years).

Cash sales at six-year high

Nationwide, all-cash purchases accounted for 34 percent of all single-family house and condo sales in the third quarter of 2021, the highest level since the first quarter of 2015. The third-quarter 2021 number was up from 33.2 percent in the second quarter of 2021 and from 21.4 percent in the third quarter of last year.

Among metropolitan statistical areas with a population of at least 200,000 and sufficient cash-sales data, those where cash sales represented the largest share all transactions in the third quarter of 2021 were Columbus, GA (74.6 percent of all sales); Atlanta, GA (69 percent); Macon, GA (59.3 percent); Youngstown, OH (56.6 percent) and Detroit, MI (56.2 percent).

Those where cash sales represented the smallest share of all transactions in the third quarter of 2021 included Lincoln, NE (15.7 percent); Greeley, CO (17 percent); Salem, OR (17.1 percent) and Washington, DC (17.2 percent) and Worcester, MA (18.7 percent).

Institutional investment up to seven-year high

Institutional investors nationwide accounted for 7.3 percent of all single-family house and condo purchases in the third quarter of 2021, the highest level since the first quarter of 2014. The latest figure was up from 5 percent in the second quarter of 2021 and was up three-fold from 2.4 percent in the third quarter of last year.

Among states with enough data to analyze, those with the largest percentages of sales to institutional investors in the third quarter of 2021 were Arizona (17.4 percent of all sales), Georgia (13.9 percent), Mississippi (12.8 percent), Nevada (12.7 percent) and North Carolina (11.3 percent).

States with the smallest levels of sales to institutional investors in the third quarter of 2021 were Hawaii (1.7 percent of all sales), Maine (1.8 percent), Vermont (2.2 percent), New Hampshire (2.5 percent) and Rhode Island (2.5 percent).

FHA-financed purchases remain at nearly 14-year low

Nationwide, buyers using Federal Housing Administration (FHA) loans accounted for only 8.3 percent of all single-family home and condo purchases in the third quarter of 2021, the second-lowest level since the fourth quarter of 2007. The latest figure was up slightly from 8.1 percent in the previous quarter but down from 11.8 percent a year earlier.

Among metropolitan statistical areas with a population of at least 200,000 and sufficient FHA-buyer data, those with the highest levels of FHA buyers in the third quarter of 2021 were Lakeland, FL (21 percent of all sales); Mobile, AL (18.3 percent); Visalia, CA (17.7 percent); Bakersfield, CA (17.3 percent) and Yuma, AZ (16.9 percent).

Lender-owned foreclosures represent just 1 percent of all sales

Home sales following foreclosures by banks and other lenders represented just 1.1 percent of all sales in the third quarter of 2021. That was down from 1.3 percent in the second quarter of 2021 and from 2.9 percent in the third quarter of last year.

Metro areas where so-called REO sales represented the largest portions of all sales in the third quarter of 2021 with a population of 200K or more and with sufficient data to analyze were Macon, GA (4.6 percent of all sales); Lansing, MI (3.1 percent); St. Louis, MO (2.4 percent); South Bend, IN (2.3 percent) and Baltimore, MD (2.3 percent).
Why a Wave of Foreclosures Is Not on the Way

Why a Wave of Foreclosures Is Not on the Way | MyKCM

With forbearance plans coming to an end, many are concerned the housing market will experience a wave of foreclosures similar to what happened after the housing bubble 15 years ago. Here are a few reasons why that won’t happen.

There are fewer homeowners in trouble this time

After the last housing crash, about 9.3 million households lost their homes to a foreclosure, short sale, or because they simply gave it back to the bank.

As stay-at-home orders were issued early last year, the fear was the pandemic would impact the housing industry in a similar way. Many projected up to 30% of all mortgage holders would enter the forbearance program. In reality, only 8.5% actually did, and that number is now down to 2.2%.

As of last Friday, the total number of mortgages still in forbearance stood at  1,221,000. That’s far fewer than the 9.3 million households that lost their homes just over a decade ago.

Most of the mortgages in forbearance have enough equity to sell their homes

Due to rapidly rising home prices over the last two years, of the 1.22 million homeowners currently in forbearance, 93% have at least 10% equity in their homes. This 10% equity is important because it enables homeowners to sell their homes and pay the related expenses instead of facing the hit on their credit that a foreclosure or short sale would create.

The remaining 7% might not have the option to sell, but if the entire 7% of those 1.22 million homes went into foreclosure, that would total about 85,400 mortgages. To give that number context, here are the annual foreclosure numbers for the three years leading up to the pandemic:

  • 2017: 314,220
  • 2018: 279,040
  • 2019: 277,520

The probable number of foreclosures coming out of the forbearance program is nowhere near the number of foreclosures that impacted the housing crash 15 years ago. It’s actually less than one-third of any of the three years prior to the pandemic.

The current market can absorb listings coming to the market

Why a Wave of Foreclosures Is Not on the Way | MyKCM

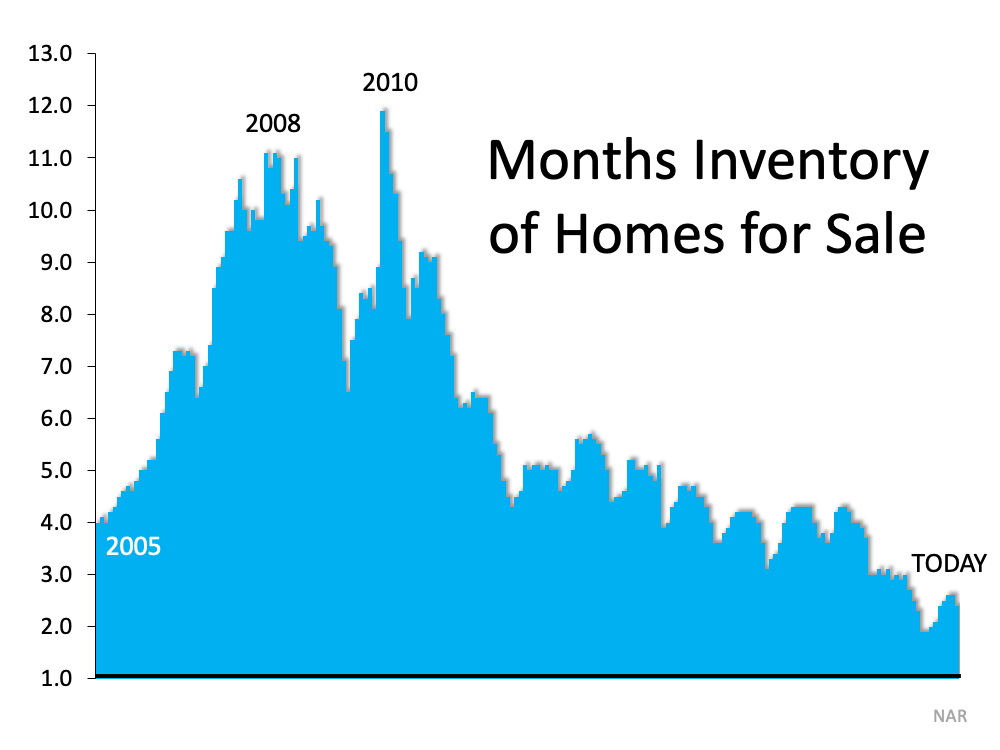
When foreclosures hit the market back in 2008, there was an oversupply of houses for sale. It’s exactly the opposite today. In 2008, there was over a nine-month supply of listings on the market. Today, that number is less than a three-month supply. Here’s a graph showing the difference between the two markets.

Bottom Line

The data indicates why Ivy Zelman, founder of the major housing market analytical firm Zelman and Associates, was on point when she stated:

“The likelihood of us having a foreclosure crisis again is about zero percent.”

Experts Project Mortgage Rates Will Continue To Rise in 2022

Experts Project Mortgage Rates Will Continue To Rise in 2022 | MyKCM

Mortgage rates are one of several factors that impact how much you can afford if you’re buying a home. When rates are low, they help you get more house for your money. Within the last year, mortgage rates have hit the lowest point ever recorded, and they’ve hovered in the historic-low territory. But even over the past few weeks, rates have started to rise. This past week, the average 30-year fixed rate was 3.14%.

What does this mean if you’re thinking about making a move? Waiting until next year will cost you more in the long run. Here’s a look at what several experts project for mortgage rates going into 2022.

Freddie Mac:

“The average 30-year fixed-rate mortgage (FRM) is expected to be 3.0 percent in 2021 and 3.5 percent in 2022.”

Doug Duncan, Senior VP & Chief Economist, Fannie Mae:

“Right now, we forecast mortgage rates to average 3.3 percent in 2022, which, though slightly higher than 2020 and 2021, by historical standards remains extremely low and supportive of mortgage demand and affordability.” 

First American:

“Consensus forecasts predict that mortgage rates will hit 3.2 percent by the end of the year, and 3.7 percent by the end of 2022.”

If rates rise even a half-point percentage over the next year, it will impact what you pay each month over the life of your loan – and that can really add up. So, the reality is, as prices and mortgage rates rise, it will cost more to purchase a home.

Experts Project Mortgage Rates Will Continue To Rise in 2022 | MyKCM

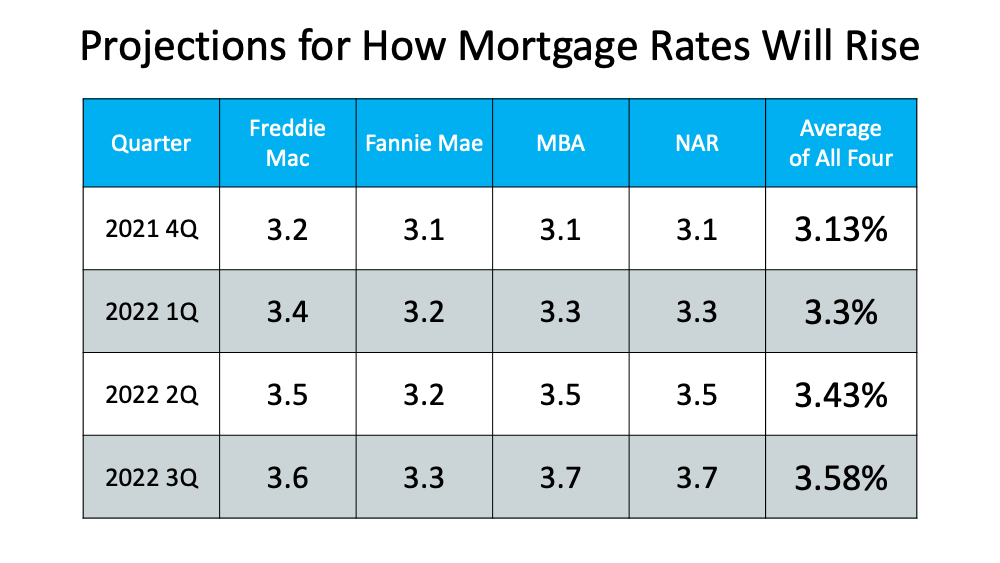
As you can see from the quotes above, industry experts project rates will rise in the months ahead. Here’s a table that compares other expert views and gives an average of those projections:Whether you’re thinking about buying your first home, moving up to your dream home, or downsizing because your needs have changed, purchasing before mortgage rates rise even higher will help you take advantage of today’s homebuying affordability. That could be just the game-changer you need to achieve your homeownership goals.

Bottom Line

If you’re thinking of buying or selling over the next year, it may be wise to make your move sooner rather than later – before mortgage rates climb higher.

Sellers Have Incredible Leverage in Today’s Market

Sellers Have Incredible Leverage in Today’s Market | MyKCM

With mortgage rates climbing above 3% for the first time in months, serious buyers are more motivated than ever to find a home before the end of the year. Lawrence Yun, Chief Economist for the National Association of Realtors (NAR), puts it best, saying:

“Housing demand remains strong as buyers likely want to secure a home before mortgage rates increase even further next year.”

But the sense of urgency they feel is complicated by the lack of homes for sale in today’s market. According to the latest Existing Home Sales Report from NAR:

“From one year ago, the inventory of unsold homes decreased 13%. . . .”

What Does This Mean for Sellers Today?

With buyers eager to purchase but so few homes available, sellers who list their houses this fall have a tremendous advantage – also known as leverage – when negotiating with buyers. That’s because, in today’s market, buyers want three things:

  • To be the winning bid on their dream home.
  • To buy before rates rise
  • To buy before prices go even higher.

Your Leverage Can Help You Negotiate Your Best Terms

These three buyer needs give homeowners a leg up when selling their house. You might already realize this leverage enables you to sell at a good price, but it also means you can negotiate the best terms to suit your needs.

And since buyer demand is still high, there’s a good chance you’ll get offers from multiple buyers who are willing to compete for your house. When you do, look closely at the terms of each offer to find out which one has the best perks for you.

If you have questions about what’s best for your situation, your trusted real estate advisor can help. They have the expertise and are skilled negotiators in all stages of the sales process.

Bottom Line

Today’s buyers are motivated to purchase a home this year, and that’s great news if you’re thinking of selling. Let’s connect today to discuss how much leverage you have as a seller in today’s market.

Renters Missed Out on $51,500 This Past Year

Renters Missed Out on $51,500 This Past Year | MyKCM

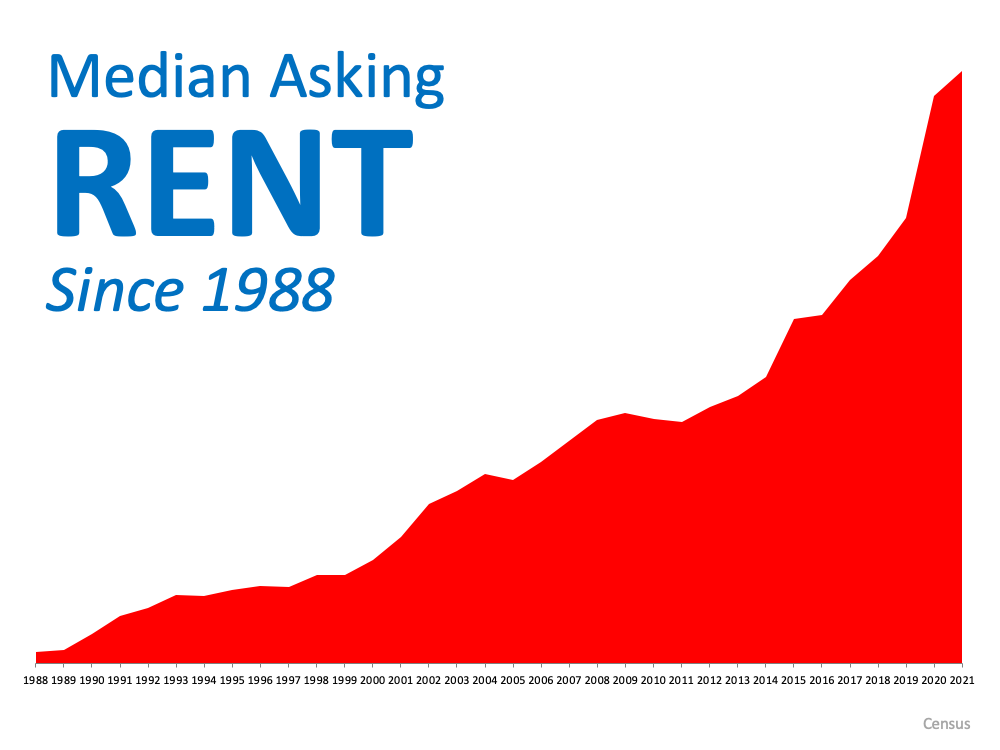
Rents have increased significantly this year. The latest National Rent Report from Apartmentlist.com shows rents are rising at a rate much higher than the three years leading up to the pandemic:

“Since January of this year, the national median rent has increased by a staggering 16.4 percent. To put that in context, rent growth from January to September averaged just 3.4 percent in the pre-pandemic years from 2017-2019.”

Renters Missed Out on $51,500 This Past Year | MyKCM

Looking back, we can see rents rising isn’t new. The median rental price has increased consistently over the past 33 years (see graph below):If you’re thinking of renting for another year, consider that rents will likely be even higher next year. But that alone doesn’t paint the picture of the true cost of renting.

The Money Renters Stand To Lose This Year

A homeowner’s monthly mortgage payment pays for their shelter, but it also acts as an investment. That investment grows in the form of equity as a homeowner makes their mortgage payment each month to pay down what they owe on their home loan. Their equity gets an additional boost from home price appreciation, which is at near-record levels this year.

The latest Homeowner Equity Insights report from CoreLogic found homeowners gained significant wealth through their home equity this past year. The research shows:

“. . . the average homeowner gained approximately $51,500 in equity during the past year.”

As a renter, you don’t get the same benefit. Your rent payment only covers the cost of shelter and any included amenities. None of your monthly rent payments come back to you as an investment. That means, by renting this year, you likely paid more in rent than you did in the previous year, and you also missed out on the potential wealth gain of $51,500 you could have had by owning your own home.

Bottom Line 

When deciding whether you should rent or buy in the future, keep in mind how much renting can cost you. Another year of renting is another year you’ll pay rising rents and miss out on building your wealth through home equity. Let’s connect today to talk more about the benefits of buying over renting.

Does Your House Have What Buyers Want?

Does Your House Have What Buyers Want? | MyKCM

The rise in remote work is changing what many Americans want in their homes. Many companies are choosing to delay reopening or go remote full-time, and today’s buyers are looking for homes with more space to support their work needs.

As a seller, if you no longer need the extra room you have in your home, rest assured there are buyers who do.

Remote Work Is Here To Stay

Remote work remains a reality for many Americans. A recent poll from Garter, Inc. shows many organizations have not yet returned their offices:

“. . . 66% of organizations are delaying reopening their offices due to new COVID-19 variants.”

And it’s not just companies that are choosing to remain remote for the time being – workers are seeking more flexibility. According to research from PricewaterhouseCoopers, nearly one-fifth of employees want to be fully remote in the future. The study also finds that many people are leaving jobs to seek out remote work opportunities:

“Among employees looking for new jobs, almost one in ten say it’s because they moved away from the office while working remotely and don’t want to go back on-site.”

More Remote Work Means a Greater Need for Home Offices

Does Your House Have What Buyers Want? | MyKCM

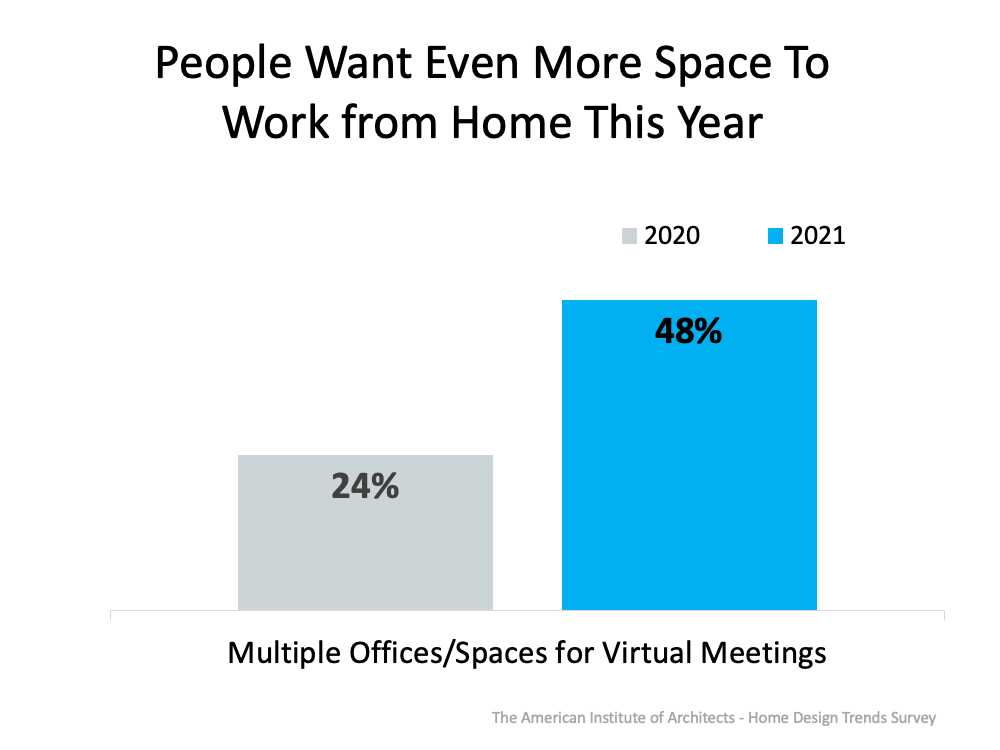
That’s leading today’s buyers to prioritize finding homes with more space so they can comfortably work from home. The 2021 Home Design Trends Survey from the American Institute of Architects finds that 69% of surveyed individuals still want at least one office at home. However, it also shows that more people are looking for multiple spaces in their home for remote work and virtual meetings (see graph below):

What Does This Mean for You?

If your house has extra space that you no longer need, buyers are interested, and now may be the perfect time to sell.

Your trusted real estate advisor can help you highlight many of the most sought-after features in your listing, including home offices. On the other hand, if you have extra room without a purpose, consider staging it as an area where remote work can happen. Your agent can help you with this as well by evaluating and preparing your space for potential buyers. They’ll make recommendations for how to stage the room, where to draw the eye, and what other sellers are doing to make their houses stand out.

Bottom Line

With the continued rise in remote work, more buyers are looking for homes that can support multiple home offices. If you have extra room you’re no longer using, consider selling. Let’s connect today to discuss the unique features in your house and how you can capitalize on any extra space to appeal to today’s buyers.